Showing posts with label Healthcare. Show all posts

Saturday, April 26, 2008

Wednesday, November 28, 2007

Hey kids!

My little monkey in the basement. He had a grand ole time running free down there.

AHHHHH ... got back last night. Needless to say, I have several mounds of laundry and a meeelllllion things to get caught up on. It was pretty cold while we were there... we had a day or two of 10 to 20 degree weather. The wind made it kind of tough on the boys working on the cabin site.

We (Mike, I should say) had a very productive 10 days! Our family cabin in coming along nicely. The load bearing wall in the basement is in place; the sub floor is up and it looks awesome; the excavator back filled around the cabin site; we now have a great burm along a much traveled county road that was put in, right along our property line (grrr) three years ago. I have some great pictures to post as soon as I have some more time. What a view, what a view, what a view we have. The pics just don't do it justice.


Logs will be delivered this coming Friday.


Casey just called me, he was told by his insurance company that the procedure on his heart will cost him 60% of the amount charged b/c it is all "out of network". GO FIGURE!!! The procedure alone will cost around $10,000, not including the hospital charges and anesthesiologist, etc.....
so, he has postponed the repair on his heart until we figure out who else he could go to that is acceptable. You know ... you don't want a "WalMart" doctor working on your heart... you'd like a "Macy's" doctor.

I'm telling ya ... our healthcare system is just a wreck. I think it's rotten that the insurance companies can dictate where you can and can't go.
By saying it's "out of network" they are pretty much saying you can't go b/c it's simply unaffordable for the average person ~ so, you are forced to go where they say.


Back when Casey was growing up, I could go where ever I wanted ... now, there is all this "in network" "out of network" crap. Back then, only the HMO's had lists of places you could and couldn't go to, now it's the regular insurance companies. Trust me, before we ever go out of town, I'm on the phone, making sure hospitals in the area are "providers" for our insurance company.


It just stinks. Poor Casey ... he's trying to get his masters degree, works full time and has a house payment on an average wage ... now, he could be facing monster medical expenses.
Makes me want to cry for him.

Wednesday, October 17, 2007

Well well....

Update to my Oct. 4th post
I spent a good portion of the day today on the phone with Apria Home Health care (and my insurance company) re: the $2443 a month payment on Matthew's feeding supplies. I was originally told, "That's what the agreement is with your insurance company". I asked for the supervisor name and number ... called her and left a lengthy message questioning the price difference.

Guess what ... they've been billing us wrong ... it should be a grand total of $849.60 ...
not $2443. They need to credit our insurance about $1593. for each month of the over billing.

*shaking my head*

Monday, June 11, 2007

Medicaid "buy in" bill did not make it thru the Senate

The bill (SB59) we were fighting for is dead. It did not make it out of Senate finance. :-(
My understanding from Medicaid is that they cannot do it this time because it was not built into their budget.

This turned into a bit of a rant, so here's your chance to go to my next happy Beaver posts.

I can just cry. Seriously. I felt that my testimony and Mike's testimony was soooo powerful. I really thought our Senators were enlightened by what is going on in the real world with real people. Apparently our testimony was not enough to bring about much needed changes in the State of Nevada, in regards to healthcare. YET!

Our state does not offer a "high risk pool" as a healthcare safety net for it's citizens...
so those that are uninsurable and those that "run out" of health insurance like we did, are just screwed. Yes, even with HIPAA protection, we were still not eligible to purchase private insurance for Matthew ~ you know ... all those loopholes.
It's all a big convoluted mess.

Why is it that 34 or 36 other states can have a high risk pool, but not a rich state like Nevada?? I can only imagine it's the lobbyists keeping this from happening.

It is very scary for families like mine that have a family member who will need a lifetime of extensive medical care. Trust me, one or two million is not enough insurance if you get a serious medical condition. Matthew blew thru 1.9 million in 10 months.

The way I feel right now... is.... whether right or wrong....

you are safe (healthcare wise) as long as you are at or below poverty level, a prison inmate or the baby of an illegal. What I have observed over the past two years, if you fall into these classifications, your healthcare is fully covered!

I'm fairly sure our politicians will never have to worry about healthcare for themselves.

If you are middle class or above, you are forced to choose a divorce, adoption or moving out of state (to another state that offers a high risk pool) for healthcare or quitting a job you love for another job in hopes of getting more insurance.


I am so disappointed!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!!

*Reminder, as of November 2006, we have a new lifetime max on our insurance... thanks to Mike's employer. We were very very fortunate. So, for now we are fine and safe! We are just trying to make a path to help others and for the future, just in case Matthew "runs out" again.

Sunday, April 8, 2007

Happy Easter!

myspace layouts, myspace codes, glitter graphics
I wanted to wish you all a very Happy and Blessed Easter!
We have so many reasons to be grateful and we are truly blessed.

We are getting ready to run over to my brothers for some good grubb'in... the whole family will be there.
Had a great few days up in Beaver w/ mom and dad ... we measured and drew out our cabin site with some orange spray paint. It's going to be sooo much fun getting this started.

Mike posted our testimony on audio to a You Tube slideshow over on Matthew's blog @ http://www.whomagoo.blogspot.com/ ...
If you watch or listen to any at all.. please listen to Mike's ... He did such a fantastic good job!
You can see the quilt he sewed and the crib he made from scratch. We sound a little like Sylvester the Cat or Daffy Duck ... the audio is a bit funny. Actually, I just added the link to my blog as well, it is below included in the testimony.

KVBC Channel 3 did have portions of our testimony on the local news at 4 and 6pm the next night.
We're so lucky to have Beth Fisher keeping the pressure on our lawmakers.

I got an e~mail from the Senator that drafted this bill... he is feeling optimistic... he and others feel it may fit into the budget! I will know on the 13th if it passed the Senate.
If it passes the Senate, it will need to pass in the Assembly.

Have a great Easter! Can't wait to run around and visit your blogs!!!!

Wednesday, April 4, 2007

Today could not have gone better!!!

I'm too tired to go into too many details, but I felt I owed you all an update!

I can say that we hit every single nail on the head! It couldn't have gone better... Senator Harry Reid's son, Rory was in the back of the room listening to our testimony. I wish he'd tell his dad. I've been writing to Harry Reid about our story for over a year. Trust me, I've written anyone who'll listen. We need changes!

The Senator that submitted this bill (he agreed to draft and submit this bill after we testified in August) sent us an e~mail telling us how great we did. He agreed that our story needs to be told. Funny thing, he's a conservative Republican (as we are) trying to do the right thing. It's never easy to introduce legislation requiring expanding the government and spending money. He sure did stick up for us middle class folks, though. I was very proud.

I ended up getting all emotional (shocker) ... and then so did Mike (bigger shocker.) We managed to keep it together though.

A local news had a cameraman there videotaping our testimony ... and might be on the news tomorrow. This news anchor has been following Matthew since before he came home from the hospital. They love him.

This whole experience was quite emotional for Mike and I ... because we know that if we run out of insurance again... we are screwed. It is absolutely true that we have no decent options in this state. The state can't deny it.

After listening to the bean counters and some others ... it sure doesn't look good for the Family Opportunity Act being passed ... or even a high-pool in the future ... for sure no Medically Needy Program! It's just like my testimony says, "Yeah, that's so sad... hum.... but it costs too much money."

What amazes me is that other states do these things .... why not this state? This is a rich state and to me there is no reason why we can't have a "safety net" for the middle class when you run out of insurance.

Well, we'll know by the 13th if it passes.


Oh, Casey's house finally "recorded" today ... five days after it was supposed to "record. " Had it been after tomorrow, he would have lost his lock in on the rates.
Thank Godfrey!!

Tuesday, April 3, 2007

Terri's testimony supporting the Family Opportunity Act

Testimony of Terri XXXX in support of Senate Bill No.59
http://www.youtube.com/watch?v=UpIuR_70Hr8&mode=related&search=

Thank you for allowing my husband and I to come and speak for a few minutes today. My name is Terri XXXX. I am a stay at home mother of a medically fragile baby and my husband is a police officer with the XXMetropolitan Police Department.

We are here today to ask for your support of the Senate Bill No.59 and to discuss further, the importance of providing a comprehensive "safety net" for all families that earn over the federal poverty level.

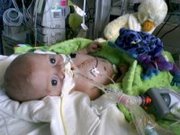
We are the parents of 23 month old Matthew XXXX. He was born 2 months premature with a rare, life threatening four-fold heart defect. The defect was determined not to be genetic and was completely beyond our control as parents. His heart defect has ballooned into a host of other medical issues.

By the time Matthew was 10 months old, he had undergone two open-heart surgeries at Lucille Packard Children’s Hospital @ Stanford . He will also require additional open-heart surgeries in the future. We are currently on a path for a third surgery, that could arise any day. How many more will he need, we do not know?

We initially felt secure that we had such good health coverage with the police department.
I am here to tell you, as a result of the extensive medical care he has received and the 6 months we spent in the intensive care units of two hospitals; 1.9 million of his 2 million dollar "lifetime cap" had been met.

Mike and I did all the right things to prepare for this baby. We took every test possible and everything appeared to be good. We united together with our family to welcome this beautiful child into our lives.

There is nothing we could have done in advance to have prevented this from happening to our baby.

We are perfect proof that a loving and responsible family can do everything right in their life, and still end up being financially ruined because of the misfortune of a catastrophic medical event.

Even worse, how can we properly care for this medically fragile child, who will need a lifetime of extensive medical care without health insurance? Even with good health insurance, these precious cardiac children are very expensive to provide for.

We once read that parents should not even file for bankruptcy until the child dies, because the medical expenses are ongoing!

We have been told that we are not eligible to purchase private insurance for various reasons. Even if we could, would we be able to afford the premiums? Mike and I were facing horrible options.

What was suggested most often, was to manipulate the system by obtaining a divorce, with my husband taking the joint assets, so I could appear to be a poor, single mother. Not only is this fraud, but it’s not the example we choose to set for our children!

A representative of The XXXX Insurance Commissioners office stated that we did have options, but we just would not like them. Our options ranged from ridiculous to outrageous. The stated options were: Move out of XXXX, to another state that offers the high-risk pool. No one should be advised by a XXXX official to leave the state, where we have resided, voted, paid taxes and built our life together with our family by our side. To us, it is no different than what Mexico does to their citizens, by encouraging them to move out and come to this country for better care.

In addition to this option, Mike "could just quit his job" that he values so dearly, and get another job, in hopes of getting more health insurance.

Lastly, we could "give Matthew up for adoption." We would not consider this at all! Why should we give our child up because he’s sick or disabled?

We have been told by many healthcare workers that if we were poor or illegal, Matthew would have qualified for full medical coverage by the state. We feel that the State of XXXX is allowing the system to be broken, by choosing to look the other way.

It gives the impression to the hard working citizens of this state that achievement is a liability and being dependant on the state is rewarded.

When my husband and I were in the Intensive Care Units’s for six months, we saw and heard of illegal alien mothers going home with Medicaid Cards for their babies.
Why is it, that the baby of an illegal alien mother, will get full healthcare coverage before our baby ~ if we were to run out of insurance?

Matthew is an American~born baby of a Gulf War Veteran who is a police officer that has served XXXX County for over twelve years. What I am saying here, is children like my son need access to medical care, as well!

We listened to one mother brag about getting full healthcare coverage for her family, FREE, because she chose not to marry her children’s father.

Can you imagine, watching your child struggle and fight for life, while you worry and fret about how you will pay the medical bills, and the mother of the child next to you, is smiling and telling you that she knew how to get her bills covered?

There needs to be something in place for families like ours. It is society’s responsibility to help those that are trying to help themselves, but are up against impossible odds.

We are not asking for hand-outs. We are willing to pay for Medicaid or a high-risk pool.

I realize XXXX is always cutting budgets because there isn’t enough money. The pie is only so big. I need for you to see the importance of making this issue a piece of that pie and allocate money to it.

Currently, it is easier to deny the program and have those families needing help move away or get divorced.

In your positions, it is easier to shake your heads and say, "Yeah, that’s too bad.... but nobody will support it."

Please do something now about this, for many legitimate XXXX families are in dire need and that need is growing.

I would like to ask you to please put yourselves in our shoes and think about what you would do, if this happened to your child or spouse and you were given the same options we were given.

Families who live in the State of XXXX who earn over the Federal poverty level need better and decent options. Just because we are not at or below the poverty level, does not mean we can afford the extensive and exorbitant medical expenses for our child.

Why doesn’t the State of XXXX have a High-Risk Pool like thirty four other states, in this day of age? Who or what is blocking this essential need??

Furthermore, why doesn’t the State of XXXX have a Medically Needy Program to help families of medically fragile children? (Such as California and Massachusetts.)

It would benefit our State to develop High-Risk Pools for the productive citizens.
These productive citizens would then continue to add to our society, and not be forced to add to the dependant burden our State is already straining to finance.

There is no one in any better position, than this senate committee to make this happen.

Thank you kindly for allowing me to talk to you.

Mike's testimony to the legislators

Testimony of Michael XXXX in Support of SB59
http://www.youtube.com/watch?v=QUcQUn0cu0Y

My name is Michael XXXX and I would first like to echo Terri’s gratitude for the opportunity to speak today. My wife has been yoked with the full burden of this issue as evidenced by her testimony.

Rather than be redundant, I would like to add my perspective as the primary breadwinner and head of household.

My son Matthew was a planned blessing. While he slumbered in the womb I read expectant mother books, painted his room, sewed him a quilt, and built his crib from scratch. I once commented to a stranger that I was nesting more than Terri was.

Anticipation gave way to concern when Matthew was born 2 months premature. The next six months our life was like the movie “Groundhog Day” where the main character is forced to relive the same day over and over. Terri & I would wake up each morning, get dressed, and drive to the hospital to sit by Matthew’s bedside.

I can tell you that our concern over all of his medical problems was enough to occupy our thoughts. I never imagined that we would also be faced with financial ruin.

Like most health insurance plans, ours carries a lifetime cap per person. Until this ordeal, I had never heard of a lifetime cap. I thought once you had insurance, you were safe.

Never one to seek a hand out, We first looked into purchasing insurance under HIPAA protection. But no one wanted to cover Matthew since they knew they would lose money. So it was at this point that we turned to the state for help. We were told that we would not qualify for assistance because I earned more than the federal poverty level.

I have never complained about my salary but I could make 20 times what I do now and still not afford Matthew’s initial medical bills.

After exhausting all other options, Terri and I went before the board of trustees for our healthcare and begged them to raise the insurance cap for their members. While not my proudest moment, it saved us from the insulting options that we would have been left with.

As the spiritual leader and provider for your household, how many of you would divorce and purposely make yourself appear to be a “dead beat Dad”?

How many of you would sign away custody of your child, thereby acknowledging your inability to provide for your family?

How many of you would uproot your spouse from her family and lose your pension to move to another state with a safety net? Are you aware that government officials and knowledgeable consultants advise your constituents to do these very things?

I pose to you, are these options you would choose if faced with this dilemma?

Ask yourself, “Is this the example I would set for my children; divorcing my spouse or filling out adoption papers?” Would you want to explain to your son or daughter, that giving them up was just on paper?

Would you spend time discussing or reiterating that mommy and daddy really do love each other, they just have to pretend so they can provide?

As it stands now there is no help in XXXX for the middle class. If you look on your pay stub you will see automatic deductions for Medicaid. In effect, we are paying into a system that we cannot benefit from. This type of income redistribution is the very definition of socialism.

I am asking you to support SB59. Though it wouldn’t help our family, there are others that would be spared the threat of financial ruin. Premiums could be set on a sliding scale based on household income.

I know you are loath to compete with private insurance companies for fear of adversely affecting their business.
I can assure you they are not seeking folks like us as customers.

The testimony that we have given today is from our recent, firsthand experiences and I thank you for listening.

Sunday, April 1, 2007

Solomon's Choice ~ Health Insurance Has It's Limits

HEALTH INSURANCE HAS ITS LIMITS.


Solomon's Choice
by Jonathan Cohn
Only at TNR Online
Post date: 10.06.06


Imagine that you have a one-year-old baby boy with a history of serious illness--and that
the boy just spiked a 103-degree fever. A physician friend recommends going to the
emergency room. Although it's a borderline case, the friend explains, it's best to play it
safe given the baby's past medical problems. You agree and start driving to the hospital.
But, on the way, you have second thoughts. You know that the emergency room will cost
a lot of money--money you really can't afford to spend. If you go the E.R. now, you
might have a harder time getting necessary care later on. Do you keep going? Or do you
turn back, hoping the baby is fine?
This is not the kind of dilemma most middle-class Americans expect to face. Yet,
because of a little-noticed coverage limitation that exists in many of America's employerprovided
health programs, Terri King says she found herself in precisely this situation a
few months ago. And therein lies yet another story of how even relatively affluent
Americans with good health insurance can run into financial trouble because of medical
illness--and about why, at some point, the government has to step in and do something
about it.
Terri and her husband, Michael, live in Las Vegas, Nevada. Michael is a veteran officer
with the city police department; Terri has worked for the greater part of her adult life,
most recently as a district trainer for a drug store chain. A little over two years ago, when
she became pregnant, she decided to stop working so that she could stay at home and
raise the baby.
It appears the Kings have always been careful financially. When I tracked down Terri
through Harvard Law School Professor Elizabeth Warren, whose TPMCafe blog first
brought the Kings' story to my attention, Terri told me that Michael makes pretty good
money--and that the two of them have never
carried significant debts other than their home mortgage.
It also appears the Kings have been careful medically. Terri was in her early 40s when
she became pregnant. Given the risks of such a pregnancy, she says, the couple was sure
to get extensive pre-natal testing to see if the baby had some congenital abnormality. This
included a close look at the baby's circulatory system.
The tests all came back fine and Terri's pregnancy appeared perfectly normal--until May
2005. That's when she unexpectedly gave birth, two months premature. At first, the boy,
whom the Kings named Matthew, actually seemed to be doing well. In fact, Terri says,
doctors told her they thought he'd go home soon. But then they discovered a serious heart
defect. Matthew had a rare disorder called Pulmonary Artesia--a deformity that prevents
proper flow of blood from the heart to the lungs
It's possible to treat the disorder by transplanting a a blood vessel (or part of one) from a
cadaver. And that's precisely what doctors at Stanford University Medical Center did
after the Kings transferred Matthew there. But, while the surgery was successful,
Matthew's lungs were severely damaged and he had to spend another six weeks at
Stanford's intensive care unit. Then it was back to the Las Vegas community hospital for
yet more inpatient care, until finally, after five months of total hospitalization, he came
home.
The Kings were grateful for the treatment. But, by this time, they were already starting to
worry about how they'd pay for it. Michael had good insurance through the police force.
But it turned out the insurance included some limits on certain catastrophic medical
expenses--among them, a $250,000 annual limit for expenses related to heart transplants.
Terri says that the Kings learned about this when a financial counselor at Stanford
informed the couple that--with Matthew's bills approaching the $250,000 threshold--their
coverage was about to run out. It came as a complete shock, she says: They had no idea
such limits even existed, let alone that they were part of Michael's coverage.
Ultimately, the Kings were able to show that the $250,000 limit was not relevant in
Matthew's case. According to Terri, the policy language referred very specifically to
whole heart transplants, rather than mere artery grafts (which is what Matthew had). But
the family's financial worries were not over. The insurance policy also included a limit on
overall expenses: $2 million for each covered person, over the course of his or her
lifetime. That may sound like a lot of money, but a baby with a serious heart defect has a
lot of medical bills. Indeed, Matthew has already been back to Stanford once for a second
open-heart surgery.
By this summer, the Kings were already within $100,000 of the lifetime limit. That is
why, on that night a few months ago, the Kings actually thought twice about bringing
their sick baby to the emergency room--after talking about it, they decided they probably
couldn't afford it. But their doctor friend had been right: Matthew was suffering from a
serious upper-respiratory infection that required hospital treatment. After consulting with
Matthew's regular physician the next day, they ended up going to the E.R. anyway.
Matthew has recovered from that infection and is, according to his mother, doing well
now. But, while his long-term prognosis is good--so far, she says, there are no signs of
serious developmental problems--he still requires extensive medication, at-home care,
and constant therapy. The total cost is a few thousand dollars a month, not including the
high expenses associated with his periodic hospitals stays.
Yet the Kings don't know where they'll get the money. So, while they hunt around for
some other source of coverage, they're holding off on any medical procedure not deemed
absolutely necessary--including an MRI that their pediatrician has recommended to check
whether Matthew suffered any mini-strokes while he was on a heart-lung machine during
his surgeries. Also on hold is surgery for Matthew's kidney reflux, a common problem in
severely premature babies.
While the Kings' medical situation is unusual, their insurance coverage is not. According
to the annual survey of employer health benefits published by the Kaiser Family
Foundation and the Health Research and Education Trust, about half of all job-based
health insurance policies have a lifetime limit. Few Americans realize this, most likely
because it's only that small fraction of people with the most serious health issues--like
Matthew King--who run up such large bills.
And yet, for those families that do hit that ceiling, there's often no recourse. Terri says
she and her husband would be happy to buy another insurance policy on their own. But,
because of Matthew's preexisting condition, private insurers don't want to sell it to them.
Michael could try to get a new job. But, even if he could find one with better insurance,
Terri says, it'd mean squandering his seniority--and, as a result, a good chunk of his
salary.
The other option would be to get insurance from the government, through the federalstate
Medicaid program. But, by design, Medicaid covers only the poor and disabled;
efforts to expand it always run into resistance from those who fear it will displace private
insurance. As a result, couples like the Kings are too wealthy to qualify. In order to get
Medicaid, they'd have to sell their house and liquidate most of their assets--or get a
divorce, with Michael taking the joint assets, so that Terri could become a poor, single
mother. (That's not some hypothetical possibility, by the way: financial counselors
suggested the divorce option. It's actually fairly standard advice in cases of high medical
expenses, as I've learned through my reporting over the years.)
For now, the Kings' best hope is to get that lifetime limit raised. In Las Vegas, police
officers like Michael get their insurance through a special benefits organization called the
Metropolitan Police Department Employee Health and Welfare Trust. The Trust, "self
insures": In other words, even though the Trust pays a private insurance company to do
the administrative work of settling claims, adjusting premiums, and so on, the actual
money to pay doctors, hospitals, and pharamaceutical suppliers comes from the Trust
itself. (The Trust, in turn, contracts with what is known as a re-insurer, which covers
unusually large claims like the Kings's.)
The Kings have been asking the Trust to raise that lifetime limit and, on Thursday, they
had the opportunity to make a personal appeal during a meeting of the Trust's board.
Although no decision is likely for at least another month, Terri said the representatives
she met seemed interested in helping. Undersheriff and Trust Chairman Douglas
Gillespie, who has been helping the Kings, later confirmed that such an increase in the
lifetime benefit is indeed under consideration.
Why wouldn't the Trust raise the limit? Most likely, because it would cost money to
cover the additional bills for Matthew and any other beneficiaries that might someday
incur such large bills. Eventually that money would have to be made up somehow--by
raising premiums or reducing benefits for everybody in the plan.
The Trust would doubtless prefer that somebody else pitch in, whether it's the hospital
(by discounting the charges for Matthew's care) or the re-insurer (by not demanding
higher premiums for greater coverage). But, of course, it's in neither party's interest to do
so. The hospitals depend on fees from insured patients like the Kings to cover other
costly services, such as training doctors and helping the indigent. The re-insurers, for
their part, depend on premiums to cover their claims payments while still making a profit.
.
That's really the fundamental problem here: Nobody wants to handle the financial burden
of Matthew's exceptionally expensive care by themselves. And, to varying degrees, none
of them really should. If insurance has one, universally agreed-upon purpose, it is to
spread the burden of such rare, catastrophic expenses to as wide a base as possible. The
case of the King family shows just how impractical that becomes when you depend upon
the self-interest of private sector institutions to accomplish this--and why, once and for
all, we need to come up with a better system.

JONATHAN COHN is a senior editor at The New Republic.

Wednesday, March 28, 2007

Life is good

myspace layouts, myspace codes, glitter graphics

All is going well! Mom found that her cancer is NOT back ... the nodule they found is just scar tissue from her previous breast cancer surgery!!! We are all so happy and truly blessed. myspace layouts, myspace codes, glitter graphics

Mike and I will be testifying before the NV legislators on Wednesday, April 4th ~ I'm anxious and nervous. I was on the phone w/ the Governor's office today, they want to hook me up with a non profit organization to help all children get health coverage. They need speakers ~ yikes!
The article about our insurance story written by a senior editor of a Washington D.C. magazine will be in an AARP magazine soon. A photographer is flying in to take pics on Wednesday. Wow!

My crazy week is going more smoothly than I had thought!! Having a great time w/ my friends from out of town. I am going to see Mamma Mia at the Mandalay Bay tomorrow night!

Friday, March 16, 2007

Testifying before the Legislators coming up


Oh Godrey, I'm nervous!

We received and e~mail from Senator Heck this week confirming that we still plan to testify before the Nevada Legislators. No doubt, we will testify. We aren't sure if we'll be able to go up to Carson City. It all depends on Matthew's health.. he's still experiencing some issues w/ his lungs and I can't go out of town unless he's 100%. The original plan was to go up to the state capital and be there in person ... but we may have to stay here and speak via teleconference. An anchor from Channel 3 news wants to be there. We're fortunate that the local news media wants to be involved. Nothing like the media to help keep on the lawmakers and the nay sayers!!

I have been told that our story is "the perfect storm" and it should help to open some eyes around here!

The Fraternal Order of Police is also helping us to lobby for much needed changes in this state. (It is all explained in my post dated Feb. 21st re: Healthcare/Health Insurance.)
A representative from the FoP has already talked to several lawmakers and is trying to set up a meeting with the Governor and/or his wife.

I have a phone conference scheduled with the General Council for Governor Gibbons on Tuesday at 10 am ... I'm very excited. I am the big ole squeaky wheel and I want to be the "John Walsh" for the middle class and above when you "run out" of health insurance or if you're uninsurable.

I have a local pediatrician on board, too ~ YAY!.... he is starting all over in his 60's after his wife suffered a stroke and lived for one year in a facility .... it wiped him out. He ended up having to divest and become her legal guardian (instead of her husband.) I actually have two other families of cardiac babies that will testify ... they also ran out of insurance, with no good options.

I just need to sit my bupp cheeps down and write out my testimony .... it will be similar to our speech back in August ~ I have to get as much power to my punch as possible!!
I want it to be perfect ... to the point ... effective.... and no rambling (I tend to do that) ... but there is so much to say!!!

I will be glad when it's over ~ it should be in the next couple weeks. I get the biggest butterflies when I think of it! :-/

P.S. A senior editor for The New Republic magazine in Washington D.C. contacted me this week (he wrote a powerful article in October about what happened to us) and he is interested in using our story for an AARP magazine article. He has a book coming out in April regarding healthcare in the U.S.

Wednesday, February 21, 2007

Healthcare/Health insurance

I'm going to "go there" because it is on my mind constantly.

I never gave healthcare/insurance a second thought, until our baby almost "ran out" of health insurance. By the time Matthew was 10 months old, 1.9 million of his 2 million dollar "lifetime cap" had been met.

Lifetime cap?? Oh.My.God. I had never heard of a "lifetime cap" in my entire life! I had raised a 22 year old without ever reaching the deductibles and I have always been very very healthy. You just think ... when you have insurance ... you have insurance, until you lose your job or discontinue your coverage. You think you are safe.

NOT always true. You should go check your policies. If you have a one million or two million cap... trust me... it's not enough if you have a major medical event. Also, they can have clauses in there that you don't know about. For three months at Stanford, we were told we were OUT of insurance b/c heart transplants had a $250,000 maximum payment... even though he didn't have a heart transplant... but a graft... the re~insurer tried to cut us off.

I think it is disgusting that in this rich country of ours ~ the middle class and above get screwed.
We middle class pay the taxes that pays for Medicaid. BUT, if we middle class "run out" of health insurance w/no options ... WE are not protected. At least if you live in Nevada. Yes, we supposedly have HIPAA to protect us... but from our experience ... the insurance companies find every single loophole possible to get out of it.

We were "not eligible" to purchase private insurance for Matthew... we fell thru every loophole the HIPAA protection had. Because we earn over the poverty level we (Matthew) didn't qualify for straight up Medicaid. "No health insurance" would be a death sentence for this boy who will need a lifetime of heart surgeries and care.

We were facing horrible and outrageous options ... such as: DIVORCE (so I could be a single, poor mother), moving out of state to another state that has a "high risk pool", giving Matthew up for adoption to a family member (saying we were unable to care for our baby), or my husband quitting the job he loves in hopes of getting more insurance at another municipality ...

WHAT IS THAT???? How crazy is that??? Makes me spit firing mad every time I think of it.

It was 18 months of a living hell (that I could never relive) ... not only worrying about the life of our medically fragile baby... but then to worry about the financial end of it at the same time... it's almost unbearable.

Luckily for us, my husband's employer raised the lifetime cap this past November. Just in the nick of time, I might add.
This was a livesaver for our family and Matthew ... I am still thrilled beyond words and thank God every chance I get.

But... this doesn't change the fact that this type of thing is happening all over this country!!

You are safe in this country if you are poor... at or below poverty level ... then you will get all the medical care you need. Medicaid pays for it all. We have seen "illegal" mothers get free healthcare for their babies and other families that went home to care for their baby with a Medicaid card. No worries for them. But, not us....forget it...."we make too much money". HA!! Anything over the federal poverty level means you make too much money. I sure don't know anyone in my life that can afford Matthews care without health coverage.

My husband and I call this "reverse distribution".

Healthcare prices are so outrageous now... no one can afford it without insurance. Holy Cow, even with insurance, these cardiac kiddo's are VERY VERY EXPENSIVE and can be quite a financial drain. It's no wonder we almost "ran out"~ because of the horrible prices our insurance paid out. Everyone should treat their health insurance as if it's a savings plan and watch every penny spent. FYI, one hospital overbilled by $130,000.

That is why we are continuing our fight to the State of Nevada. We are going to testify to our legislators soon. We testified in August of last year and persuaded Senator Joe Heck(R) to draft and submit a "Medicaid buy~in " bill... unfortunately there is an income cap ... so we would not qualify. This bill will help 40+ Nevada families, I hope it passes.

We need something to protect the middle class families.

We need changes in our healthcare system. No one should ever face what we faced.

Here is an eye opening link:
http://www.washingtonpost.com/wp-dyn/articles/A9447-2005Feb8.html?sub=AR
Article written by Elizabeth Warren, a Harvard law professor called...Sick and Broke.

Photobucket - Video and Image Hosting